‘CJ Logistics looks up’
CJ Logistics will gain as delivery costs rise and global business improves, said Kiwoom Securities on Sept. 13, maintaining a “buy” recommendation and 220,000 won (US$196.17) target price.
From the Equity Insider archive. This article dates from Sep 13, 2018 and is preserved as first published.
CJ Logistics will gain as delivery costs rise and global business improves, said Kiwoom Securities on Sept. 13, maintaining a “buy” recommendation and 220,000 won (US$196.17) target price.
CJ Logistics will gain as delivery costs rise and global business improves, said Kiwoom Securities on Sept.
Its revenue in the third quarter will hike 27.2 percent on-year to 2.38 trillion won while operating profit will decline 6.3 percent to 58.7 billion won. It has secured new clients for overseas business and will maintain stable growth but will have to bear rising costs from beginning operations of a delivery terminal in Gyeonggi Province. As for its global business, initial costs are stabilizing, and in addition to expanding client base, earnings from its newly acquired US subsidiary DSC Logistics will partially be reflected, said analyst Lee Chang-heui.
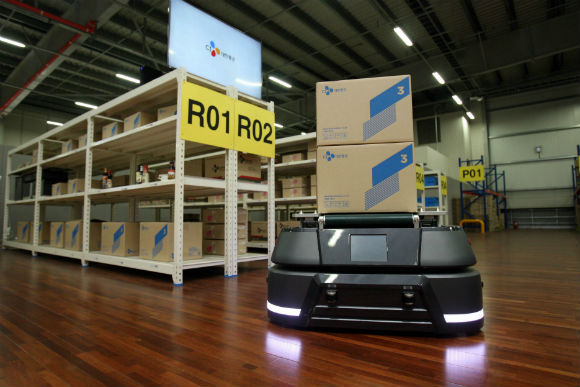
From the latter half, delivery sector will gain as it will be able to handle more volume from operating a new terminal and prices will increase. Being the domestic market leader with over 50 percent share, aggressive rise of prices will definitely boost its profits, but it will need more time before the industry is fully reorganized and will be able to raise the price by 15 percent, as Japan’s Yamato did, he added.